Turns out there's no magic number that makes someone financially independent, and the reason why might surprise you.
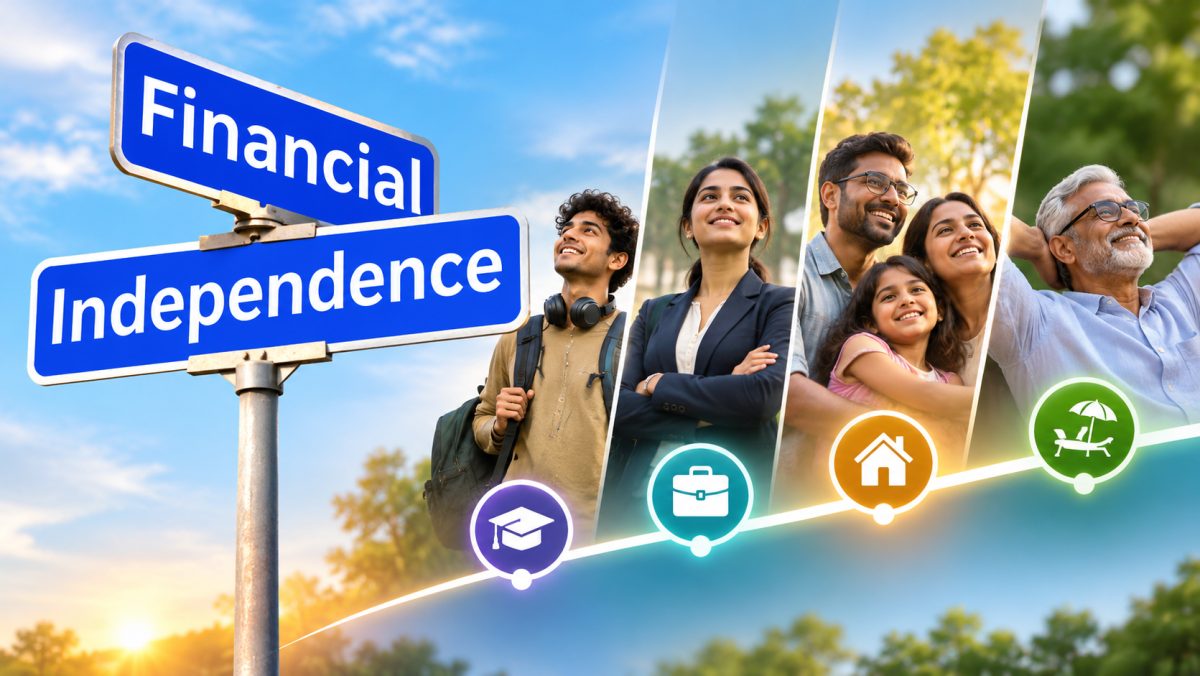
Financial independence looks different depending on who you ask, and that is the whole point of a growing conversation among financial planners and everyday savers alike. For a college graduate, it might mean paying rent without help from mom and dad. For a retiree, it might mean having enough saved up to never need a paycheck again. There is no single dollar figure that fits everyone, and experts say that is exactly why so many people get confused trying to find one.
Iowa AG Brenna Bird Sues Dollar General Over Register Overcharges
Why Financial Independence Shifts With Every Life Stage
View this post on Instagram
A young adult just starting out usually measures financial independence by simple things. Can they cover rent? Can they pay for groceries and bills without calling home for help? That is often the first real taste of standing on your own two feet financially.
Mary Ware, a certified financial planner based in Charlotte, North Carolina, says the definition keeps changing as people age. "Financial independence means different things to different people," Ware said. She added that "it depends on your stage of life," pointing out that a twenty-something and a retiree are solving completely different money puzzles, even though they use the same phrase to describe their goal.
For couples, financial independence often takes on a different shape entirely. It is less about paying bills alone and more about keeping personal savings intact and having the ability to cover your own expenses even if a relationship ends. Maintaining that kind of independence inside a partnership has become its own area of financial planning, separate from the retirement-focused version most people picture.
Waco Financial Empowerment Center Opens Doors to Free Money Help for Everyone
The Retirement Version Looks Nothing Like the Young Adult Version
By the time someone nears retirement, financial independence usually means something much bigger than covering a monthly rent check. It means having enough saved in investments, pensions, or other income sources to cover living costs without relying on a full-time job. This is the version most closely tied to the idea of retiring comfortably and never needing another paycheck.
Older adults also have to think about risks that younger people rarely consider. Long-term care costs, medical bills, inflation, and the possibility of losing a spouse all factor into whether someone truly has enough. Greg Welborn, another financial adviser, frames the entire concept around control rather than a specific number. "Financial independence is controlling your own future," Welborn said, describing it as something you arrive at rather than a fixed point you hit. He called it "arriving at a situation, not a point," stressing that the real test is whether someone can handle a sudden loss of income without falling apart financially.
That distinction matters because two people can have the exact same amount of money saved and still be in very different positions. Someone with no debt and steady income is in a stronger spot than someone with the same savings but heavy credit card balances or an unpredictable paycheck. Net worth alone does not tell the whole story.
Why a Single Dollar Amount Does Not Work for Everyone
Location and lifestyle play a massive role in what financial independence actually costs. Someone living simply in a low-cost area might need far less saved up than someone raising kids in an expensive city with high rent and childcare bills. A general definition says financial independence means having enough income from savings, investments, or passive sources to cover living expenses without depending on a job, but the actual number behind that definition swings wildly based on where you live and how you spend.
This is part of why the financial independence conversation often gets tangled up with the FIRE movement, which stands for financial independence, retire early. FIRE followers tend to save aggressively and invest heavily so they can stop working sooner, sometimes decades before a traditional retirement age. Traditional financial planning takes a wider view, factoring in insurance, emergency funds, debt payoff, and protection against future surprises. Both paths lead toward the same general idea, but they get there in very different ways.
Independence From Work Does Not Always Mean Quitting Work
One of the more surprising parts of this discussion is that financial independence does not require someone to stop working altogether. For many people, reaching that milestone simply makes work optional. It opens the door to switching careers, cutting back hours, caring for family members, going back to school, or taking a lower-paying job that feels more meaningful.
That flexibility is really the heart of the idea. Money stops being the thing controlling every decision, and choice takes over instead. Someone could keep working the same job they always had, not because they have to, but because they want to. That shift, more than any specific bank balance, is what separates financial independence from simply having a lot of money saved.
Planners generally agree that building toward this goal means looking honestly at spending habits, debt levels, emergency savings, and future health costs, then testing whether those numbers hold up if a paycheck suddenly disappeared. There is no universal formula and no single finish line. The target moves depending on age, relationship status, location, and how much risk a person is willing to carry, which is exactly why the same three words mean something different to nearly everyone who uses them.