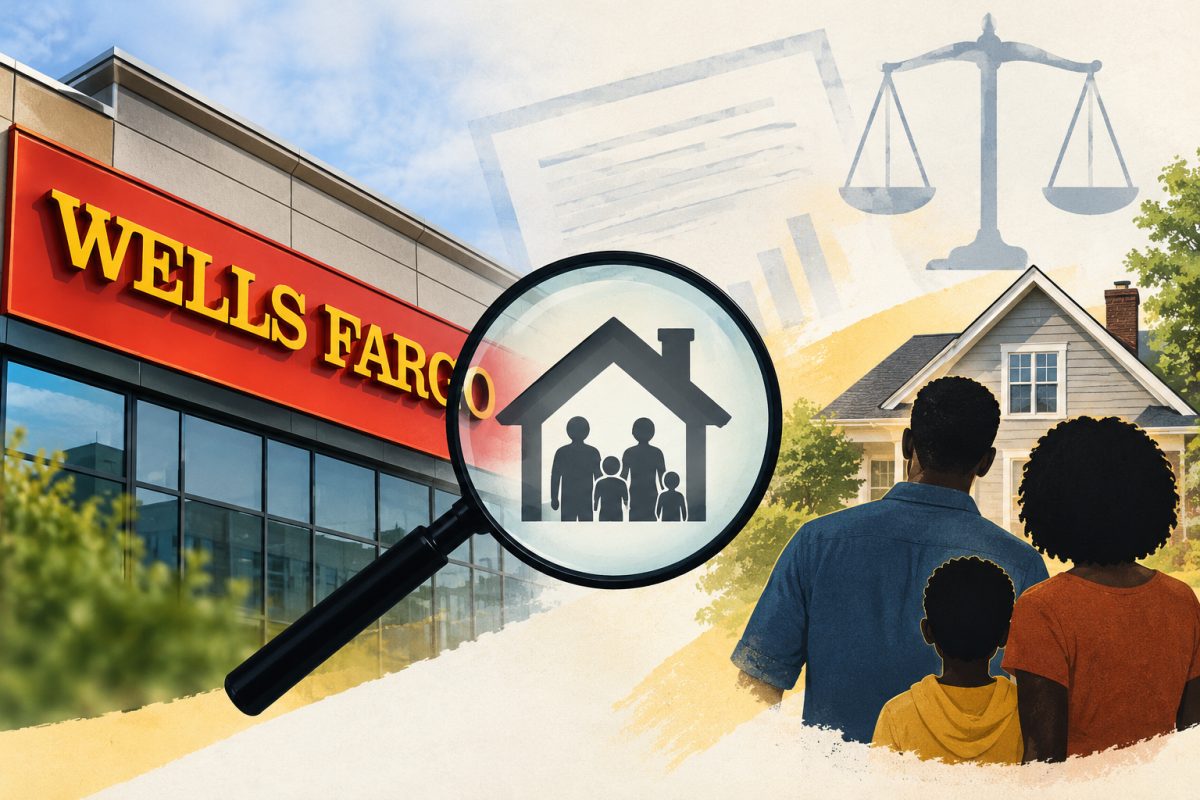
Federal housing officials are scrutinizing nearly ten years of Wells Fargo commitments to Black homebuyers, raising questions about where racial-equity lending ends and illegal discrimination begins.
The U.S. Department of Housing and Urban Development has opened an inquiry into whether Wells Fargo violated federal fair-lending law through programs designed to boost Black homeownership, according to a letter sent Wednesday, Oct. 7, 2026, to Wells Fargo Chief Executive Charlie Scharf. The investigation, first reported by The Wall Street Journal, examines whether the bank unlawfully favored Black and other minority borrowers by offering race-specific products, refinancing discounts, or different loan terms, according to Reuters and The New York Times. The inquiry is at an early stage, and no legal violation has been established.
Where Manchester City's £900m 'Inflated' Money Actually Went in the Transfer Market
How the Inquiry Was Triggered
The investigation was outlined in a letter authored by Craig W. Trainor, HUD's assistant secretary for Fair Housing and Equal Opportunity, who reportedly cited Wells Fargo's "repeated public promotion of explicit race-based policies," according to The New York Times. The letter accused the bank of adopting a strategy of "sorting" homeowners and offering different products or terms based on race, a characterization echoed in reporting from the Washington Examiner.
Investigators are focused specifically on initiatives aimed at Black homeowners, including a reduced-cost refinancing program and a $150 million credit initiative described as advancing racial equity in homeownership, according to Newsmax. The Fair Housing Act bars discrimination in mortgage lending based on race, color, religion, sex, familial status, national origin, or disability, and HUD's position suggests that race-conscious remedies intended to close homeownership gaps could themselves trigger legal exposure if they sort applicants or deliver materially different treatment by race.
Chennai Man Deposited ₹85 Lakh Cash, But Why Did ITAT Reject the Taxman's Doubts?
A Decade of Racial-Equity Commitments Now Under the Microscope
The scrutiny follows years of public pledges by Wells Fargo to narrow the racial homeownership gap. In 2017, the bank announced a plan to lend $60 billion by 2027 with the goal of helping create at least 250,000 African American homeowners. It is not clear from available reporting how the bank counted qualifying borrowers or measured progress toward that target, nor whether it functioned as a race-exclusive lending quota or a broader access initiative.
In 2022, Wells Fargo announced a $210 million program to help Black clients reduce mortgage rates and refinancing costs, justified at the time by citing "systemic inequities" that prevented many minority families from building wealth through homeownership, according to National Mortgage News. A separate $100 million commitment followed in 2023 to advance racial equity through nonprofit partnerships and community programs. Reports also reference a distinct $150 million initiative, and available accounts do not fully reconcile whether these figures represent overlapping programs or separate funding streams.
Officials Stake Out Combative Positions
HUD Secretary Scott Turner said the department planned a full investigation and criticized policies that, in the administration's view, divide Americans by race, according to National Mortgage News and the New York Post, which reported Turner described such efforts as "immoral" and "un-American." A senior HUD official told The Wall Street Journal that similar programs at other banks are also under review, a detail that signals the Wells Fargo case may be an early test of how aggressively federal regulators intend to challenge corporate diversity, equity, and inclusion programs tied to financial products, as noted by MPA Magazine.
Wells Fargo has not been reported to have admitted wrongdoing, and no formal enforcement complaint, monetary penalty, consent order, or court proceeding has been identified in available coverage. The unresolved legal question is whether the bank's programs used race as a direct eligibility condition or instead targeted communities affected by documented disparities in credit access and mortgage pricing — a distinction that could determine whether regulators treat the initiatives as prohibited disparate treatment or permissible remedial outreach.
Markets React as Industry Faces Wider Uncertainty
Wells Fargo shares fell following news of the HUD inquiry, though available reporting does not specify an exact percentage decline or confirm the investigation as the sole cause of the stock movement, according to the New York Post. Potential consequences for the bank include legal costs, document-production demands, revised eligibility criteria, reputational fallout, and pressure to suspend or redesign the affected programs.
The case lands at a pivotal moment for the broader mortgage industry, which for years has promoted targeted lending programs to address the legacy of redlining, unequal credit access, and disparities in loan approval and pricing. HUD's approach could reshape how banks structure mortgage discounts, down-payment assistance, refinancing subsidies, and community lending targets designed for historically underserved groups, according to National Mortgage News.
What Comes Next for Wells Fargo and the Industry
Investigators are expected to examine program documents, eligibility standards, marketing materials, loan-level data, internal communications, and how the bank treated applicants outside the targeted groups. HUD may ultimately close the matter, demand program changes, negotiate a settlement, or pursue formal enforcement action, though none of those outcomes has been announced.
For Wells Fargo, the scrutiny arrives as the bank approaches its self-imposed 2027 deadline for the $60 billion lending pledge first announced in 2017. For consumers, the immediate impact remains uncertain, but programs offering reduced refinancing costs or other race-targeted assistance could face modification or discontinuation if HUD concludes they impermissibly rely on race as a qualifying factor. At this stage, the investigation represents regulatory scrutiny rather than proven discrimination, with the ultimate legal and financial conclusions still pending.